
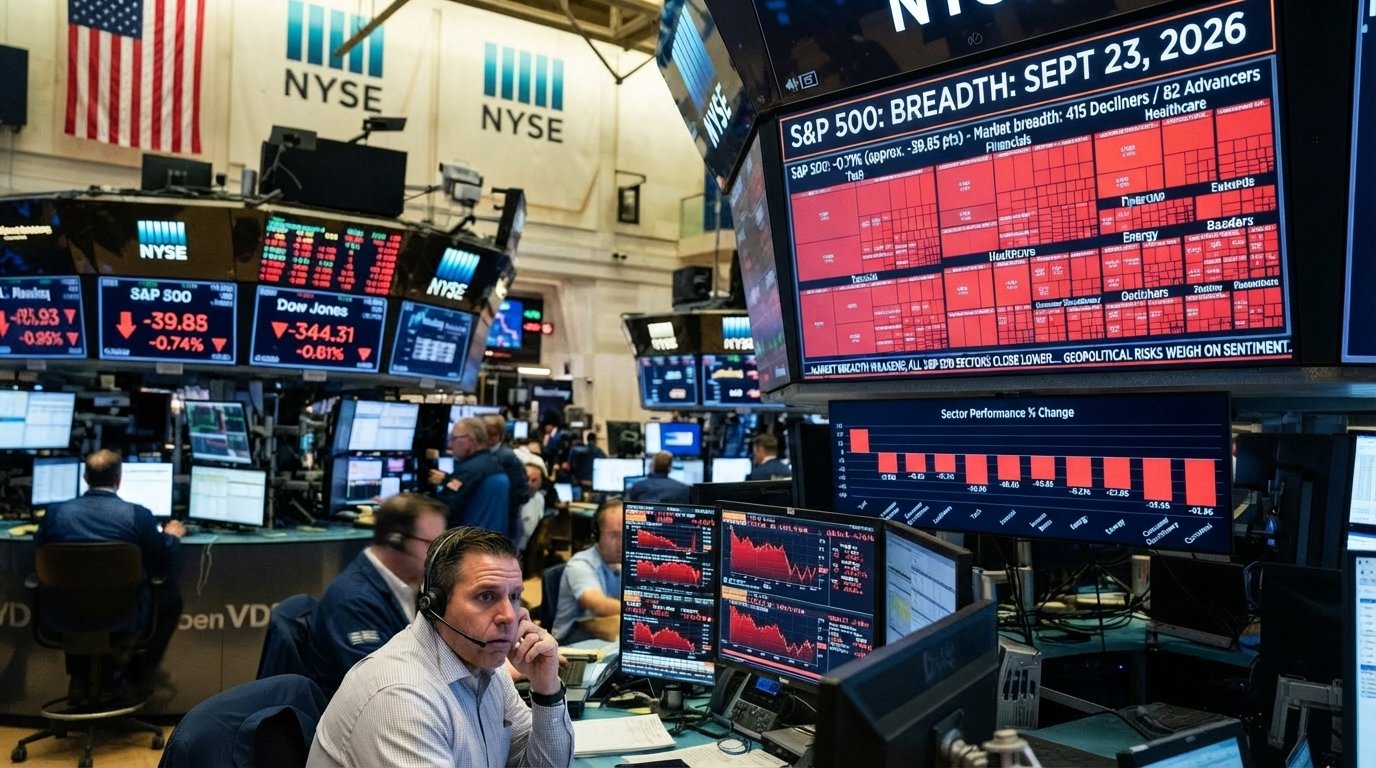
For generations, utility stocks were the bedrock of income portfolios: steady businesses, regulated returns and reliable dividends. In 2026, they have become one of the market’s biggest disappointments. According to Finviz, the Utilities sector fell another 1.83% on Wednesday, Sept. 23, and is now down on every timeframe the site tracks — one week, one month, one quarter, six months, one year and year to date.
The culprit is not a collapse in demand for electricity. It is the rise of a formidable competitor for income investors’ money: the U.S. Treasury, which now pays more than 5% on its 10-year note for the first time since 2007.
Utilities: A Year of Losses
| Timeframe | Utilities | Real Estate | Consumer Defensive |
|---|---|---|---|
| Sept. 23 | −1.83% | −1.50% | −0.35% |
| Week | −2.64% | −1.32% | −0.12% |
| Month | −6.82% | −7.37% | −3.47% |
| Quarter | −12.23% | −5.79% | −2.72% |
| Half Year | −11.31% | +3.78% | +0.56% |
| 1 Year | −5.85% | −0.36% | +5.30% |
| YTD | −6.69% | +3.37% | +5.34% |
Utilities’ 12.23% decline over the past quarter is the worst of any sector over that period. For a group that is traditionally considered low-risk, that is a substantial drawdown — larger than the typical annual dividend yield many utilities pay.
The Math of “Bond Proxies”
Utilities, real estate investment trusts and consumer staples companies are often called “bond proxies” because investors buy them largely for their predictable income. Their share prices tend to move inversely to interest rates, much like bonds.
The reasoning is simple. When a 10-year Treasury yielded 2% or 3%, a utility paying a 4% dividend offered a clear income advantage, plus the potential for dividend growth. Now that the 10-year Treasury yields roughly 5.1% and the 2-year about 4.9%, that advantage has shrunk or disappeared. Investors can earn a comparable or higher yield from a government bond with no equity risk. To remain competitive, utility share prices must fall until their dividend yields rise to a more attractive level.
Finviz valuation data show the Utilities sector trades at a trailing P/E of 17.78 and a forward P/E of 15.04, implying earnings yields of about 5.6% and 6.7%, respectively. Price-to-book is 1.91. Those valuations are not extreme, but with analysts expecting only 10.70% annual EPS growth over the next five years — among the lowest of any sector — investors are unwilling to pay a premium in a high-rate world.
A Double Hit From Borrowing Costs
Utilities are among the most capital-intensive businesses in the economy. They continually borrow to build and upgrade power plants, transmission lines and distribution networks. When interest rates rise, their financing costs rise too. Regulated utilities can eventually pass some of those costs to customers through rate cases, but the process takes time, and regulators may resist large increases when households are already facing high energy bills.
The strain is visible internationally as well. Bloomberg reported this week that creditors of Britain’s Thames Water are planning a new rescue deal to avert state control — an extreme example of how a heavily indebted utility can struggle when the cost of capital rises.
The AI Power Paradox
There is a striking irony in utilities’ weak performance. Demand for electricity is expected to grow rapidly as AI data centers come online. One analysis circulated this week estimated the earnings potential of 25 gigawatts of AI computing capacity by 2030, a scale that would require enormous amounts of power. In theory, that should be a powerful tailwind for utilities.
So far, however, rising rates have overwhelmed that growth story. Related industries have also stumbled: Finviz shows the Uranium industry — often seen as a play on nuclear power for data centers — down 13.04% over the past month and 3.86% on Wednesday. Meanwhile, the companies building AI infrastructure directly, such as distributors in Finviz’s Electronics & Computer Distribution industry (up 92.87% YTD), have captured far more investor enthusiasm. Worthington Enterprises reached a new high on Wednesday amid demand for data center cooling.
For long-term investors, this disconnect may eventually present an opportunity. If rates stabilize, utilities with strong exposure to data center demand could re-rate higher. But timing that shift depends heavily on the Federal Reserve.
Real Estate and Consumer Defensive
Real Estate has also struggled, down 7.37% over the past month, with the Office REIT industry falling 3.00% on Wednesday. One Seeking Alpha analysis on Finviz argued that Realty Income, known for its monthly dividend, has become attractive again after falling to year-to-date lows. Real Estate carries the highest PEG ratio of any sector on Finviz, at 2.84.
Consumer Defensive has held up better, falling only 0.35% on Wednesday — the smallest decline among sectors that fell — and remaining up 5.34% year to date. Staples companies benefit from pricing power, and many have less debt than utilities. However, the sector’s PEG ratio of 2.66 and forward P/E of 19.68 suggest it is not cheap. Costco, one of the sector’s most closely watched companies, reports earnings after Thursday’s close.
What Income Investors Are Doing
The shift in yields is prompting income investors to rethink their strategies:
- Treasury bills and short-term bonds now offer yields near 5% with minimal risk, making them a direct competitor to dividend stocks.
- Covered-call ETFs have gained popularity as a way to boost income from equities; one blog featured on Finviz this week reviewed the highest-yielding covered call ETFs that have avoided NAV declines.
- Financial-sector dividend payers, such as insurers, may benefit from higher rates. Finviz shows Insurance – Reinsurance up 16.20% YTD and Insurance – Diversified gaining on Wednesday.
- Energy dividend payers have been supported by strong cash flows; Energy’s forward earnings yield is about 8.2% based on Finviz data.
What Would Turn Utilities Around?
The most likely catalyst would be a peak in interest rates. Markets currently price roughly 60% to 71% odds of another Fed rate hike in October, and the Fed’s dot plot shows 16 of 19 officials expecting at least one more hike this year. Once investors become confident that rates have topped out, bond proxies historically tend to recover — sometimes sharply.
Other catalysts could include clear evidence of AI-driven load growth translating into higher allowed returns, favorable regulatory decisions or a flight to safety during an economic downturn.
For Policymakers and Economists
Utilities’ struggles have real-world implications. The energy transition and AI-driven load growth both require massive investment in power generation and transmission. Higher capital costs make that investment more expensive, which ultimately means higher electricity bills for consumers or slower infrastructure buildout. Policymakers balancing inflation control against energy security and grid reliability face a genuine trade-off — one that will become more acute if rates continue to rise.
For now, the message from the market is clear: in a world of 5% Treasuries, dividends alone are no longer enough.
Data source: Finviz sector performance, sector valuation and industry data as of the Sept. 23, 2026 close; headlines via Finviz news and blogs feeds (Bloomberg, Seeking Alpha, MBI Deep Dives, Dividendology). Yields from TheStreet and Benzinga. This article is for informational purposes only and is not investment advice.