
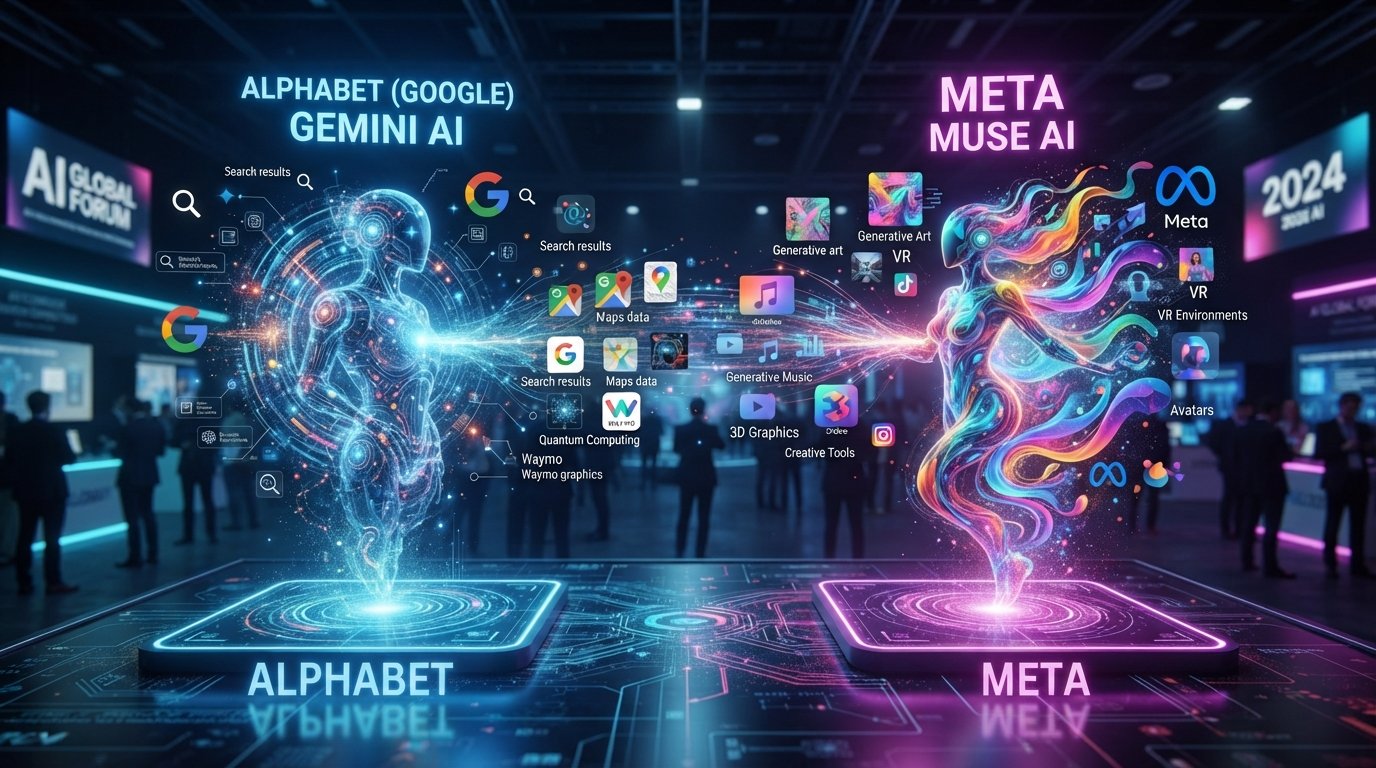
A new front has opened in the artificial intelligence race, and Wall Street is already trying to pick winners and losers. On Wednesday, Sept. 23, 2026, shares of Alphabet fell sharply while Meta Platforms moved higher, as investors digested Mark Zuckerberg’s comments that Meta’s new personal AI agent, Muse, will take “a small fee” on transactions it completes for users.
According to Finviz, Alphabet Class A (GOOGL) fell 3.80% and Class C (GOOG) dropped 3.58%, making the search giant one of the worst-performing mega-cap stocks on a day when the broader market was already under pressure from rising Treasury yields. Meta (META) rose 1.02%, one of the few large technology names to finish in positive territory.
What Is Muse, and Why Does It Matter?
Muse is Meta’s consumer AI agent — software designed not just to answer questions but to take actions on a user’s behalf, such as researching products, booking travel or completing purchases. Yahoo Finance reported that the Muse app reached the top of Apple’s App Store, a sign of rapid early adoption. Zuckerberg’s comment that Meta will take a cut of transactions signals that the company sees agents as a direct revenue stream, not just an engagement tool.
Reuters summarized the market reaction in a headline carried on Finviz: “Meta’s Muse rekindles fears over winners and losers as personal AI agent emerges.” The logic is straightforward. If consumers increasingly ask an AI agent to find and buy things rather than searching the web themselves, the traditional path from search query to advertisement to click to purchase could be disrupted.
Why Alphabet Took the Hit
Alphabet’s core business is built on that traditional path. Search advertising depends on users typing queries and clicking on paid links. An AI agent that bypasses the search results page — and collects its own fee from merchants — is a potential threat to that model. The market’s reaction on Wednesday suggests investors are pricing in at least some risk that agent-driven commerce could erode Google’s dominance in high-value commercial searches.
It is important to keep this in perspective. Alphabet has its own AI assistants and agents and enormous distribution through Android, Chrome and YouTube. YouTube CEO Neal Mohan said in an interview this week that the company is “betting on AI and not afraid of it.” A single day’s decline does not settle a competitive battle that will play out over years. But it does show how sensitive valuations have become to any sign that AI could reshape existing profit pools.
The Ripple Effect Across E-Commerce and Travel
Alphabet was not alone. Finviz data show other companies whose business depends on owning the customer relationship also fell:
- Amazon (AMZN): −2.24%
- Shopify (SHOP): −3.66%
- Netflix (NFLX): −1.11%
The most striking move came at the industry level. Finviz’s Travel Services industry — which includes online travel agencies — fell 4.06% on Wednesday. It is now down 7.63% over the past week, 21.14% over the past month and 18.75% year to date. Online travel booking is precisely the kind of multi-step, comparison-heavy task that AI agents are designed to handle, and investors have been rapidly repricing the sector as agent technology improves.
Yahoo Finance also noted that Muse’s rise intensified concerns about disruption to financial services. Finviz’s Advertising Agencies industry fell 3.07% on the day and is down a remarkable 45.03% year to date, the kind of collapse that reflects deep investor concern that AI will reduce the need for traditional ad buying and creative services.
Market commentators are exploring second-order effects too. One investment blog featured on Finviz this week asked, “If Muse is buying your running shoes, what happens to Nike?” The question gets at the heart of the issue: if an AI agent chooses products based on price, reviews and specifications, brand loyalty built through advertising could matter less.
Communication Services in Context
Alphabet and Meta both sit in Finviz’s Communication Services sector, which fell 1.82% on Wednesday. The sector has gained just 1.00% year to date, far behind Technology’s 29.65%, although it is up 8.91% over the past six months. It trades at a trailing P/E of 18.08 and a forward P/E of 19.72 — cheaper than tech on a trailing basis, reflecting the market’s uncertainty about how AI will reshape advertising-driven business models.
The sector’s valuation is also notable for what it implies: a forward P/E higher than the trailing P/E suggests analysts expect earnings to dip or grow slowly in the near term, possibly because of heavy AI capital spending.
The Bigger Picture: AI Moves From Building to Charging
For much of the past three years, the AI trade has focused on the builders: chipmakers, data center operators and cloud providers. Muse represents a shift toward monetization at the consumer level. Meta is not the only company moving in this direction. A research note from App Economy Insights this week examined “OpenAI’s advertising machine,” highlighting how AI platforms are building their own commercial models.
This transition matters because the massive infrastructure spending of the past few years eventually needs to earn a return. A blog post on Finviz this week noted that Nebius “raised prices again,” with $7.8 billion in investment that now “has to earn its keep.” Investors are increasingly asking not whether AI works, but who captures the profits.
Implications for Policymakers
AI agents that sit between consumers and merchants raise significant competition and consumer protection questions. If a single platform’s agent handles a large share of purchasing decisions, it could exert enormous influence over which merchants succeed. Transaction fees charged by agents could also be passed on to consumers in the form of higher prices. Regulators in the U.S. and Europe will likely scrutinize how agents rank products, disclose fees and handle payment data. A Seeking Alpha piece on Finviz this week, focused on Cognizant, argued that “rogue AI agents need guardrails” — a view that is likely to gain traction in policy circles.
What Investors Should Consider
- Disruption risk is being priced quickly. Travel Services down 21% in a month shows how fast sentiment can shift when a new technology threatens an established business model.
- Platform owners may benefit. Companies with large user bases and the ability to deploy agents directly — such as Meta — may capture new revenue.
- Don’t overreact to a single day. Alphabet remains one of the most profitable companies in the world, with its own AI products and distribution advantages.
- Watch adoption metrics. App Store rankings are an early indicator; transaction volumes and merchant partnerships will be more meaningful.
Wednesday’s divergence between Meta and Alphabet was a small move in the context of multitrillion-dollar companies. But it may be remembered as an early marker of the next phase of the AI trade — one in which the battle is over who controls the consumer’s decision, not just who builds the smartest model.
Data source: Finviz quote, sector, industry and valuation data as of the Sept. 23, 2026 close; headlines via Finviz news and blog feeds (Reuters, Yahoo Finance, Big Technology, App Economy Insights, Seeking Alpha). This article is for informational purposes only and is not investment advice.