
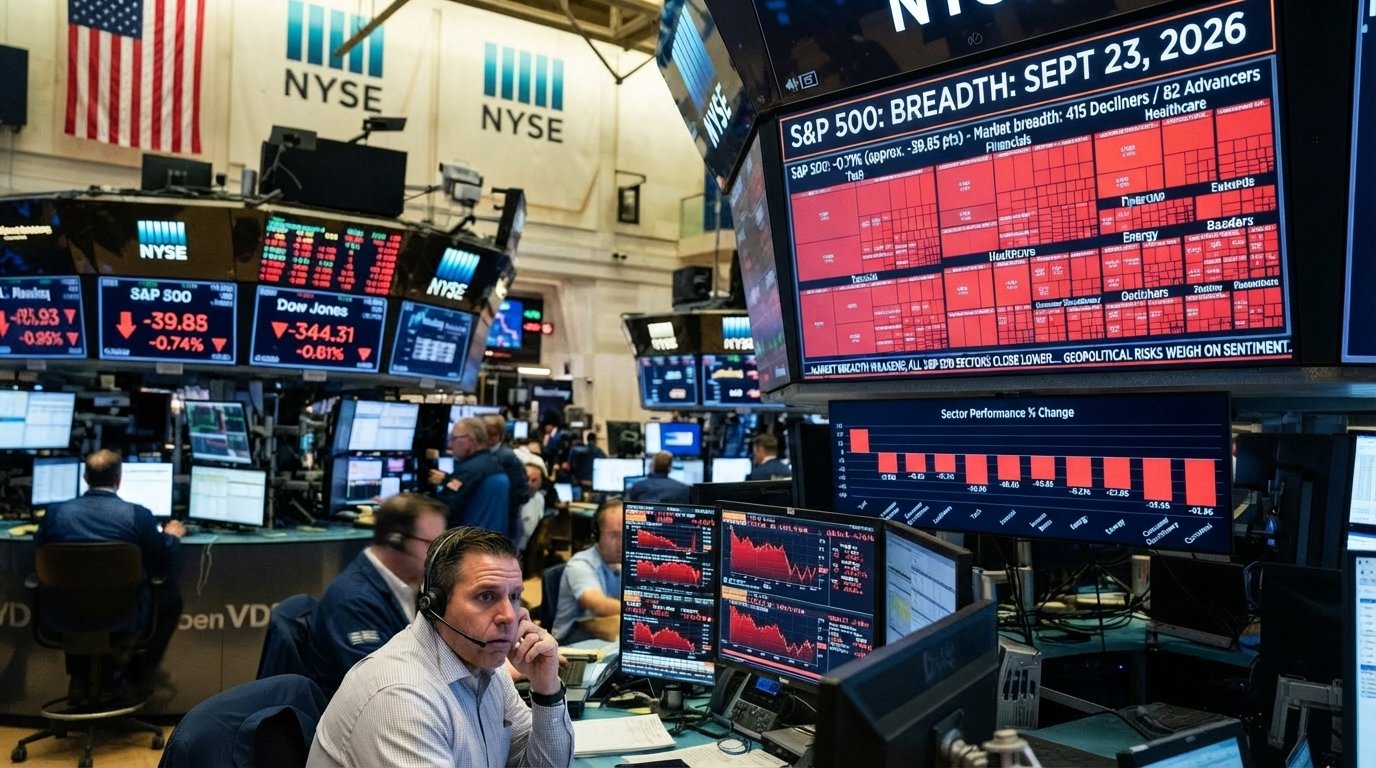
Headline index moves often hide what is really happening in the stock market.
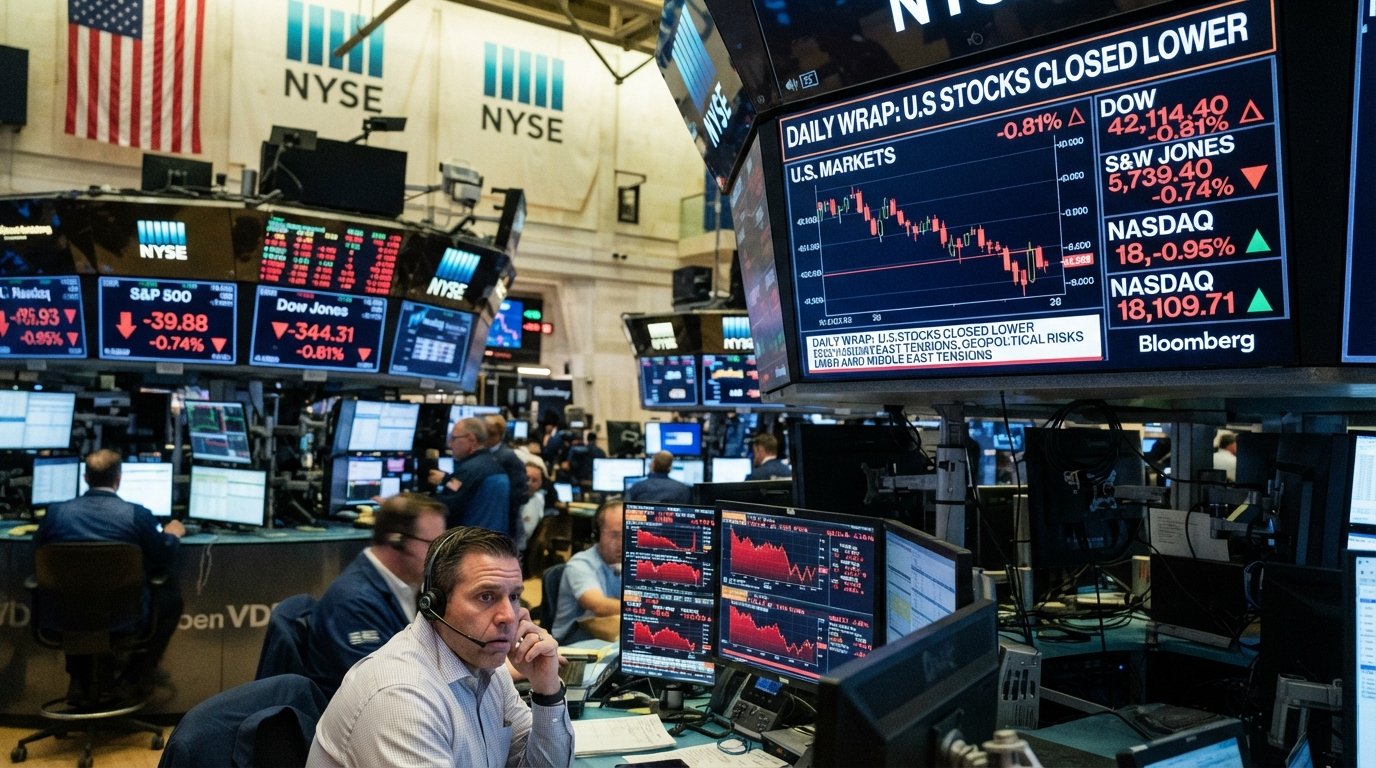
Market breadth: Sept. 23, 2026, the S&P 500 fell roughly 0.7%.
Nevertheless, breadth on Finviz reveals a troubling story: nearly three out of four U.S.-listed stocks finished lower.
Breadth measures how many stocks participate in a market move. When an index rises while most stocks fall, leadership is narrow. When an index falls and almost everything falls with it, selling is broad and indiscriminate. Consequently, Wednesday was firmly in the second category. Market breadth: Sept. 23, 2026, the S&P 500 fell roughly 0.7%.
The Numbers Behind the Selloff
Finviz’s breadth panel, which covers stocks listed on the NYSE, NASDAQ and NYSE American, showed the following at the close:
| Indicator | Stocks | Percentage |
|---|---|---|
| Advancing | 1,349 | 24.1% |
| Declining | 4,050 | 72.2% |
| New 52-week highs | 77 | 19.6% |
| New 52-week lows | 316 | 80.4% |
| Above 50-day SMA | 1,817 | 32.5% |
| Below 50-day SMA | 3,778 | 67.5% |
| Above 200-day SMA | 2,386 | 42.6% |
| Below 200-day SMA | 3,209 | 57.4% |
Additionally, the advance/decline ratio is about 1 to 3.
For every stock that rose, three fell.
Market breadth: Sept. 23, 2026, the S&P 500 fell roughly 0.7%, and that was a decisive reading.
Why Breadth Matters More Than the Index
The major U.S. indexes are weighted by market capitalization. That means a handful of mega-cap technology companies account for a large share of the S&P 500 and an even larger share of the Nasdaq 100. On any given day, a strong move in a few of those names can mask weakness across hundreds of smaller companies.
This dynamic has been especially pronounced in 2026.
Moreover, Market breadth: Sept. 23, 2026, the S&P 500 fell roughly 0.7%.
A Reuters headline on Finviz this week observed fewer stocks carrying the market.
Finviz’s capitalization data reinforce the point, unlike at the dot-com peak.
Mega-cap stocks gained 10.38% year to date and 18.42% over the past six months.
Micro caps are down 0.88% year to date and mid caps have returned 7.35%.
When breadth is narrow in a rising market, the risk is that leadership eventually tires and there is little underneath to support the index. When breadth collapses in a falling market, as it did Wednesday, it signals that investors are reducing exposure across the board rather than simply rotating from one theme to another.
The Moving Average Picture
Perhaps the most telling figures on the Finviz dashboard are the moving-average readings. Only 32.5% of stocks — 1,817 names — are trading above their 50-day simple moving average. That means more than two-thirds of the market is in a short-term downtrend, even though the Nasdaq Composite set a record close as recently as Tuesday.
The longer-term picture is somewhat healthier but still weak. Just 42.6% of stocks, or 2,386 names, trade above their 200-day moving average, while 57.4% sit below it. The 200-day line is widely used by institutional investors to define a primary trend. When a majority of stocks sit below it, the “average stock” is in a bear-market posture regardless of what the headline index says.
That gap — a Nasdaq near record highs while most stocks trend lower — is the clearest possible illustration of the market’s narrow leadership. Technology is the only sector on Finviz with a positive one-month return of any size (+7.88%), and it has gained 37.50% over the past six months. Meanwhile, Utilities are down 12.23% over the quarter, Real Estate is down 7.37% over the month and Basic Materials is down 7.36% over the month.
New Highs Versus New Lows
The new-high/new-low data add another layer. Market breadth: Sept. 23, 2026, the S&P 500 fell roughly 0.7%. Additionally, On Wednesday, Finviz recorded 316 new 52-week lows against 77 new highs. Notable new lows included ADGM down 53.04% to $0.23. Additionally, VII down 50.88% to $4.46, DCX down 29.69% to $0.07, and LPG down 29.56% to $1.00.
The handful of new highs came from a narrow set of names, including TJGC (up 37.75% to $23.28), CBAT (up 13.18% to $1.46), VNCE (up 9.57% to $11.11) and Worthington Enterprises (WOR), which closed at $59.70, up 1.29%. Worthington has been benefiting from investor enthusiasm around data center cooling demand.
Market technicians often watch whether new lows expand while an index is still near its highs. That divergence has historically been an early warning sign of a more serious correction, though it is not a timing tool on its own and can persist for weeks or months.
Where the Selling Was Concentrated
Finviz’s capitalization breakdown shows that smaller companies bore the brunt of Wednesday’s selling:
- Small cap: −2.33%
- Micro cap: −2.04%
- Nano cap: −1.85%
- Mid cap: −1.34%
- Mega cap: −1.06%
- Large cap: −0.76%
Smaller companies tend to carry more floating-rate debt and have less access to capital markets, so a jump in yields hits them harder. At the industry level, the worst performers were those most exposed to rates, credit or falling metals prices: Silver (−7.24%), Other Precious Metals & Mining (−4.67%), Mortgage Finance (−4.32%), Gold (−4.09%), Travel Services (−4.06%) and Uranium (−3.86%).
What Breadth Tells Different Audiences
For investors: A single weak breadth day is not a signal to abandon a long-term plan. But persistently weak participation, combined with a rising cost of capital, argues for checking portfolio concentration. Many index investors now hold far more mega-cap technology exposure than they realize.
For market watchers and traders: The key things to watch in coming sessions are whether the percentage of stocks above the 50-day moving average stabilizes near current levels or continues to fall, and whether new lows keep outnumbering new highs. A quick rebound in breadth would suggest Wednesday was a one-day rate shock; continued deterioration would suggest something more structural.
For policymakers: Broad equity weakness tightens financial conditions, which is effectively what the Federal Reserve is trying to achieve after raising rates to 3.75%–4.00% on Sept. 16. The Fed watches financial conditions closely, and a sustained broad-based decline in stock prices would do some of the central bank’s work for it.
For economists: The divergence between strong economic data — September’s composite PMI reached 58.4, the highest in more than five years — and deteriorating market breadth reflects a classic late-cycle tension: good news for growth is being read as bad news for rates.
The Bottom Line
Wednesday’s breadth readings were among the weakest this month.
However, 72.2% of stocks declined.
Sixty-seven point five percent were below their 50-day averages.
New lows outnumbered new highs by roughly four to one.
This suggests the market’s internal health is worse than the major indexes indicate.
Market breadth: Sept. 23, 2026, the S&P 500 fell roughly 0.7%.
Data source: Finviz breadth, capitalization, industry and signal data as of the Sept. 23, 2026 close. This article is for informational purposes only and is not investment advice.